How to Calculate Future Value
What Is Future Value?
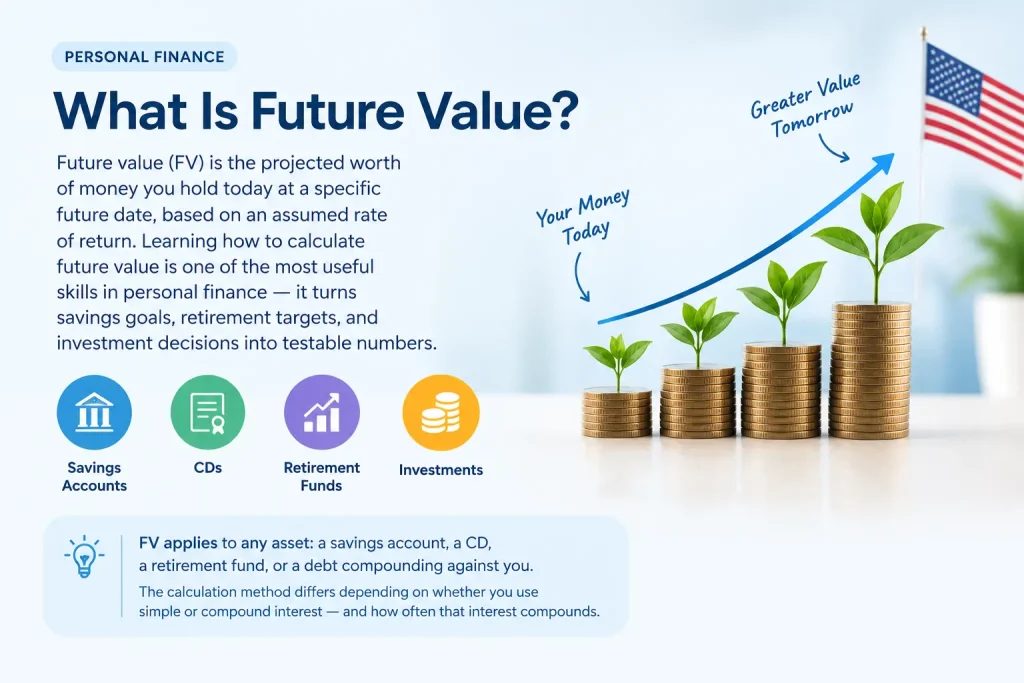
Future value (FV) is the projected worth of money you hold today at a specific future date, based on an assumed rate of return. Learning how to calculate future value is one of the most useful skills in personal finance; it turns savings goals, retirement targets, and investment decisions into testable numbers. FV applies to any asset: a savings account, a CD, a retirement fund, or a debt compounding against you. The calculation method differs depending on whether you use simple or compound interest and how often that interest compounds.
Financial foundation first. Before projecting investment growth with FV, clear high-interest debt (above 7–8% APR) and build a 3–6 month emergency fund. Compounding works both ways; debt grows faster than most investments.
Key Takeaways:
The Future Value Formulas
Four formulas cover every real-world FV scenario. Each one fits a specific situation: lump sum, regular savings, advanced modeling, or annuity planning. If you want to skip the manual math and run the numbers instantly, our CD Calculator handles compounding calculations for savings instruments in seconds.
Formula 1 — Simple Interest
Use when interest is calculated only on the original principal, not on accumulated interest.
FV = PV \times (1 + r \times n)
Variables:
Formula 2 — Compound Interest
Use when interest earns interest on itself each period. This is the standard for most savings accounts, bonds, and long-term investments.
FV = PV \times (1 + r)^{n}
For compounding more than once per year (monthly, quarterly, etc.):
FV = PV \times \left(1 + \frac{r}{m}\right)^{n \times m}
Additional variable:
Formula 3 — Continuous Compounding
Used in advanced finance, derivatives pricing, and theoretical models. Interest compounds at every infinitely small moment.
FV = PV \times e^{r \times t}
Variable:
- e = Euler’s number ≈ 2.71828
- t = time in years
Formula 4 — FV With Regular Periodic Contributions
The most practical formula for real-world savings. Use this when you make regular deposits (monthly savings, 401(k) contributions, etc.) in addition to an initial lump sum
For contributions made at the end of each period (ordinary annuity):
FV = PV \times (1+r)^{n} + PMT \times \frac{(1+r)^{n} – 1}{r}
Additional variable:
- PMT = payment amount per period
Quick Reference: If your savings account earns a stated annual rate of 6% compounded monthly, your effective annual rate (EAR) = (1 + 0.06/12)^12 − 1 = 6.168%. Always use EAR for accurate comparisons.
Step-by-Step Calculation Examples
Example 1 — Simple Interest
Scenario: You invest $5,000 in a fixed-rate savings instrument paying 6% simple interest per year. How much will you have after 5 years?
Formula: FV = PV × (1 + r × n)
- FV = $5,000 × (1 + 0.06 × 5)
- FV = $5,000 × 1.30
- FV = $6,500
You earn $1,500 in total interest. Interest accrues only on the original $5,000 each year.
Example 2 — Compound Interest (Annual)
Scenario: Same $5,000, same 6% rate, but now compounded annually for 5 years.
Formula: FV = PV × (1 + r)^n
- FV = $5,000 × (1.06)^5
- FV = $5,000 × 1.3382
- FV = $6,691.13
Compounding adds $191.13 more than simple interest over just 5 years. Over 30 years, that gap becomes enormous.Compounding Frequency: Same Rate, Different Results Here is what happens to $5,000 at 6% over 5 years when you change only the compounding frequency.
| Compounding | Formula | FV |
|---|---|---|
| Simple interest | PV × (1 + r × n) | $6,500.00 |
| Annual compound | PV × (1 + r)^n | $6,691.13 |
| Monthly compound | PV × (1 + r/12)^60 | $6,744.25 |
| Continuous | PV × e^(rt) | $6,749.29 |
Monthly compounding beats annual by $53.12. Continuous compounding is the theoretical ceiling; the gap above monthly is minimal in practice. CDs are a textbook example of this. If you want to see how compounding frequency affects a certificate of deposit, read our guide on how to calculate CD rates.
Example FV With Regular Monthly Contributions
Scenario: You invest $5,000 today and add $200/month for 10 years at 7% annual interest, compounded monthly.
Step 1—FV of the lump sum:
- r = 0.07/12 = 0.005833 monthly
- FV₁ = $5,000 × (1.005833)^120 = $10,048.49
Step 2 — FV of monthly contributions:
- FV₂ = $200 × [(1.005833)^120 − 1] / 0.005833 = $34,600.95
Total FV = $44,649.44
Total deposited: $29,000. Investment growth: $15,649.44.
Inflation, Tax Drag, and Hidden Fees: What Erodes Your FV
Nominal FV is what the math gives you. Real FV is what you can actually spend. The gap between them is where wealth silently disappears.
Inflation: The Real Future Value Formula
Inflation reduces the purchasing power of your future dollars. A 7% nominal return in a 3% inflation environment leaves you with a 3.88% real return, not 7%.
Real FV Formula:
FV_{real} = \frac{FV_{nominal}}{(1 + inflation\ rate)^{n}}
Example: You invest $10,000 at 7% for 20 years.
- Nominal FV = $10,000 × (1.07)^20 = $38,696.84
- Real FV (assuming 3% inflation) = $38,696.84 / (1.03)^20 = $21,427.02
Inflation costs you $17,269 in purchasing power. Your portfolio nearly quadrupled on paper, but in real terms it just overdoubled.
Use the Fisher Equation for precise real rate calculation: Real rate = [(1 + nominal rate) / (1 + inflation rate)] − 1
Tax Drag on Investment Returns
Most investors overlook how taxes compound against them. This is especially true for interest-bearing accounts like CDs, where earnings are taxed as ordinary income each year, not at the lower capital gains rate. Understanding how to calculate CD interest helps you see exactly what the IRS takes before projecting your real FV.
Three tax scenarios on the same $10,000 at 7% over 20 years:
| Account Type | Tax Treatment | FV After 20 Years |
|---|---|---|
| Tax-deferred (401k/IRA) | Tax on withdrawal only | ~$35,000–$38,696 |
| Tax-exempt (Roth IRA) | No tax on growth or withdrawal | $38,696 |
| Taxable account (24% bracket) | Annual capital gains tax | ~$28,000–$32,000 |
Note: Taxable account estimates vary based on holding period, dividend frequency, and tax-loss harvesting. Consult a CPA for your specific situation.
Rule of thumb: A 1% annual tax drag over 20 years reduces FV by approximately 18%.
Investment Fees: The Silent Wealth Killer
A 1% annual management fee sounds small. Over time, it is not.
$10,000 invested at 7% for 30 years:
A 2% annual fee destroys 43% of your final wealth compared to a zero-fee scenario. Always check the expense ratio before investing.
Future Value of Annuities
An annuity is a series of equal, regular payments. Two types exist — and they produce different FV results.
Ordinary Annuity (Payments at End of Each Period)
Most common type. Mortgage payments, bond coupons, and typical retirement contributions work this way.
FV = PMT \times \frac{(1+r)^{n} – 1}{r}
Example: You deposit $500 at the end of every month into a savings account paying 6% annually (0.5% monthly) for 10 years.
Total deposited: $60,000. Earnings from growth: $21,939.67.
Annuity Due (Payments at Beginning of Each Period)
Each payment is made at the start of the period, giving every deposit one extra period of growth. Rental income, lease payments, and certain pension plans use this structure.
FV = PMT \times \frac{(1+r)^{n} – 1}{r} \times (1+r)
Same numbers as above, but payment made at the start of each month:
- FV = $81,939.67 × 1.005
- FV = $82,359.37
The annuity due yields $419.70 more simply by shifting the payment timing to the start of the period.
When to use each: Use the ordinary annuity formula for monthly savings deposits and retirement contributions. Use the annuity due formula when payments are made upfront rent collected as a landlord, lease payments, or insurance premiums paid at the start of the period.
Future Value vs Present Value
FV and PV are two sides of the same time-value-of-money equation. One moves money forward in time; the other moves it backward.
| Concept | Question It Answers | Direction | Formula |
|---|---|---|---|
| Future Value | What is $X today worth in N years? | Present → Future | FV = PV × (1+r)^n |
| Present Value | What is $X in the future worth today? | Future → Present | PV = FV / (1+r)^n |
They are mathematically reversible. If FV = $13,000 at 5% over 5 years, then:
- PV = $13,000 / (1.05)^5 = $13,000 / 1.2763 = $10,183.98
And working forward:
- FV = $10,183.98 × (1.05)^5 = $13,000 (rounds to same figure)
When to use each:
Practical Example: You want $50,000 for a house down payment in 7 years. Your investment earns 6% annually. How much do you need to invest today?
- PV = $50,000 / (1.06)^7 = $50,000 / 1.5036 = $33,250.85
Invest $33,250.85 today at 6%, and you will reach $50,000 in exactly 7 years.
Benefits and Limitations of the FV Formula
What FV Does Well
What FV Gets Wrong (And How to Fix It)
| Limitation | The Problem | The Fix |
|---|---|---|
| Assumes constant rate | Real returns vary year to year | Run 3 scenarios: conservative (4%), base (7%), optimistic (10%) |
| Ignores inflation | Nominal FV overstates purchasing power | Always calculate real FV: FV_nominal / (1+inflation)^n |
| Ignores taxes | Returns in taxable accounts are reduced by capital gains tax | Use post-tax returns (nominal rate × (1 − tax rate)) |
| Ignores fees | A 1% fee shaves ~18% off your 20-year FV | Always use net-of-fee return as your rate input |
| Single rate for all periods | Not realistic for variable-rate investments | Use Monte Carlo simulation for probabilistic FV ranges |
| Cannot compare unequal investments | A bigger FV does not always mean a better investment | Use NPV or IRR for investment comparison, not FV alone |
The Fully Adjusted FV Formula
For the most accurate real-world FV, account for all four factors:
FV_{adjusted} = PV \times \left(\frac{1 + r_{gross} – fees}{1 + inflation}\right)^{n} \times (1 – tax\ rate)
This is the FV that matters. Everything else is a projection on paper.
Frequently Asked Questions
The Bottom Line
Future value is the most important calculation in personal finance. It turns abstract goals—retirement, a house, your child’s education into concrete numbers you can plan around.
What to remember:
Use the formulas in this article, the Excel FV function, or a dedicated calculator to model your own scenarios. The math is straightforward. The discipline to act on it is where most people fall short.